The Unofficial Credit Card Application Rules You Need to Know (Bank-by-Bank Guide)
This post contains affiliate and referral links. If you apply for a credit card through our links, we may earn a referral bonus or commission at no extra cost to you. We only recommend cards we genuinely use and love. Thanks for supporting Ryan & Kate’s Mile Report!
When Kate and I first got into points and miles, we assumed a good credit score and on-time payments were basically the whole game. We had no idea that banks actually have strict credit card application rules running behind the scenes. Apply, get approved, collect the bonus. Easy, right?
Turns out, no. Not even close.
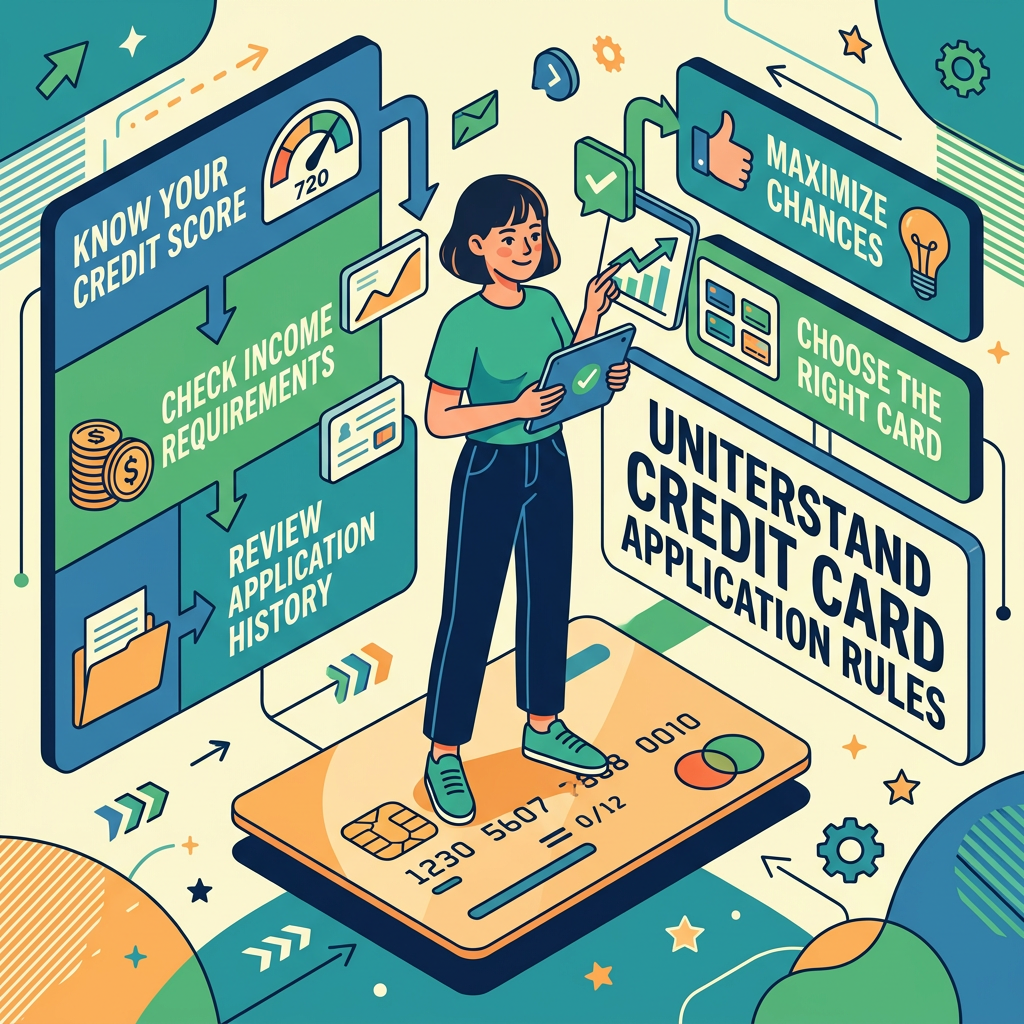
Behind the scenes, every major bank runs its own unwritten playbook designed specifically to stop people from opening card after card. Don’t know the rules going in, and you’ll burn a hard inquiry for nothing, get an instant denial, or accidentally torch a bonus you didn’t even realize you were eligible for. So here’s our full bank-by-bank breakdown — everything we wish someone had told us on day one.
1. Chase: The Infamous 5/24 Rule (and a Few Others)
Chase makes some of our favorite cards in the game — the Chase Sapphire Preferred among them — which is exactly why getting their rules right matters so much.
The 5/24 Rule
Open 5 or more personal credit cards from any bank in the last 24 months, and Chase will auto-decline you. No exceptions, no appeals.
- What counts: personal cards from any issuer — Chase, Amex, Capital One, Citi, store cards like Target or Amazon, even authorized-user cards someone added you to.
- What doesn’t count: most business cards. Chase, Amex, and Citi business cards generally don’t report to your personal credit report, so they stay off your 5/24 count entirely.
- The move: apply for Chase cards first, before you touch anything else. Once you’re past 5/24, you’re locked out until your oldest cards age past that two-year mark.
Velocity and Family Rules
- 2/30 rule: Chase typically won’t approve more than 2 cards (or 1 business card) inside a 30-day window.
- Sapphire Rules: You can now hold both the Chase Sapphire Preferred and
Chase Sapphire Reserve at the same time. However, welcome bonuses on each
Sapphire card are strictly once-per-lifetime—meaning if you’ve earned the bonus
on a specific Sapphire card in the past, you won’t be eligible for that same
card’s bonus again. - Southwest rule: one personal Southwest card at a time, though a personal and business Southwest card together is fine.
2. American Express: Once-in-a-Lifetime, and Order Really Matters
Amex approves fairly generously, but they’re strict about who actually gets paid the bonus.
- The lifetime rule: you can generally only earn a given card’s welcome offer once per lifetime — in practice, that resets after roughly 7 years.
- The family rule — and this one trips people up: apply for the Amex Platinum first, and you’ll lock yourself out of the welcome bonus on Gold or Green later. The rule flows downward from whatever’s most premium, so the smart sequence is Green → Gold → Platinum if you want to catch every bonus along the way.
- The pop-up warning: before you submit, Amex will flag you with a pop-up if you’re not bonus-eligible. See it, and you can back out with zero credit hit — worth reading before you hit submit, not after.
- Velocity limit people forget about: Amex generally won’t approve more than 2 new cards in any 90-day window, regardless of which cards they are.
- Card cap: you’re capped around 4–5 personal/business credit cards at once (charge cards like Gold and Platinum, which have no preset spending limit, are counted separately and allow for more).
3. Capital One: Strict Spacing, All Three Bureaus
Capital One pulls your credit from all three bureaus — Equifax, Experian, and TransUnion — on every single application. Keep that in mind before you apply just to “see what happens.”
- The 6-month rule: generally one approval every 6 months, personal or business combined.
- 2-card cap: most people top out around 2 personal Capital One cards.
- The Venture family rule: earned a bonus on the Venture or Venture X in the last 48 months? You’re not eligible for a VentureOne bonus until that clock runs out.
- Business card warning: unlike Chase or Amex, most standard Capital One business cards — everything except the Venture X Business and Spark Cash Plus — do report to your personal credit and will count toward your Chase 5/24.
4. Citi: The 8/65 Rule and Long Memory on Bonuses
Citi’s limits are straightforward once you’re tracking the calendar:
- 8/65 rule: no more than 1 Citi application every 8 days, and no more than 2 within any 65-day window — personal and business combined.
- 48-month bonus rule: for major card lines like the Citi Strata Premier, you’re locked out of a repeat bonus for 48 months after your last one on that same card.
If You Get Denied: Call Reconsideration (Where It Actually Exists)
A denial isn’t necessarily final. A lot of the time, the bank just wants to verify your identity or income, or you can offer to shift some credit line from an older card over to the new one.
Here’s where it’s worth being honest: not every bank actually runs a reconsideration line. Chase, Amex, and Citi do — real people reviewing denied files. Capital One doesn’t run a true recon process; calling in typically just gets your application reprocessed, which triggers a brand-new hard pull rather than a second look at the original one.
- Chase Personal Recon: 1-888-270-2127
- Chase Business Recon: 1-800-453-9719
- Amex Reconsideration: 1-800-567-1083
- Citi Reconsideration: 1-800-695-5171
- Capital One: 1-800-625-7866 (general customer service — expect a reprocess with a new pull, not a true reconsideration)
When you get someone on the phone, keep it simple: “Hi, I submitted an application recently and it wasn’t automatically approved — is there anything I can clarify or provide to help move it along?”
Bottom Line
It’s a lot to hold in your head at first, but a simple spreadsheet of your application dates (or an app like Travel Freely) makes it effortless to track. Hit Chase first, respect each bank’s spacing rules, and you’ll stop leaving bonuses on the table by accident.